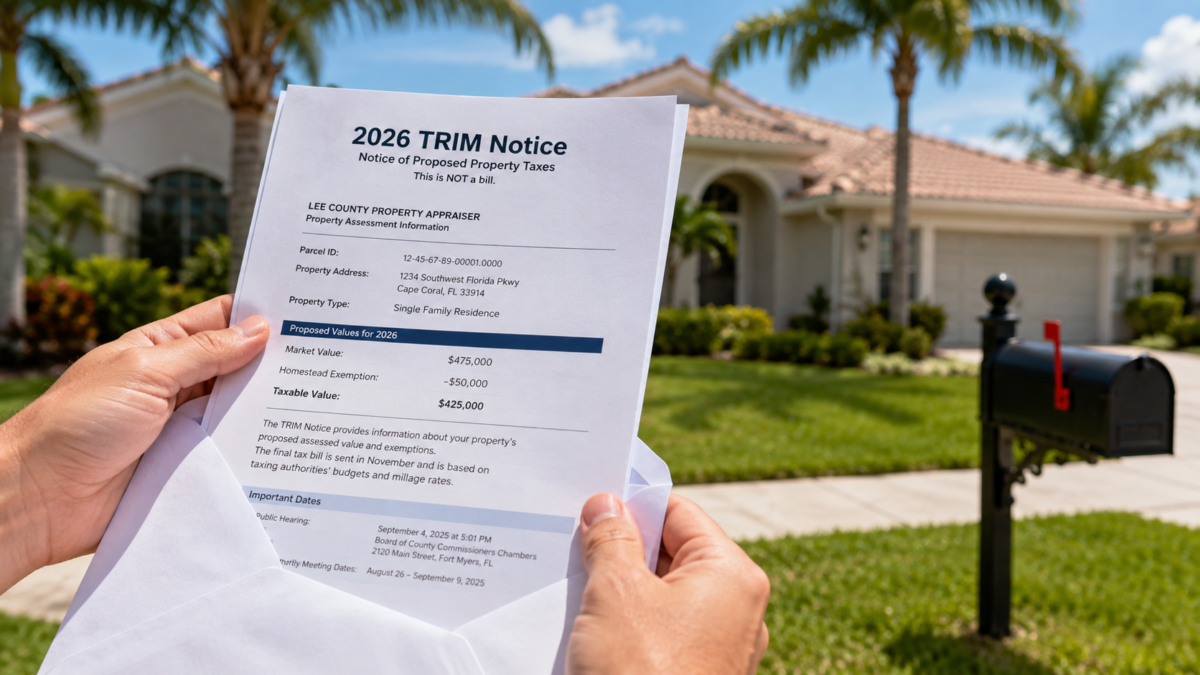
It is that time of year again across Southwest Florida. The Lee County Property Appraiser has begun mailing the official 2026 TRIM (Truth in Millage) Notices to all real estate owners throughout Sanibel, Captiva, Fort Myers, Cape Coral, and the surrounding barrier islands.
A TRIM Notice is not a tax bill—rather, it is a detailed estimate showing your property’s preliminary market valuation, assessed valuation, applied exemptions (such as the Florida Homestead Exemption), and proposed local tax millage rates for the upcoming fiscal year.
At the LeAneSuarezGroup, we view your TRIM Notice as an important annual baseline. Monitoring assessed values against current market activity ensures your real estate portfolio stays aligned with local market conditions.
How to Read Your 2026 TRIM Notice
When your document arrives in the mailbox, take a few minutes to evaluate four key components:
                    TRIM NOTICE CORE COMPONENTS

  [ MARKET VALUE ]    ──► The Property Appraiser's estimate of value as of Jan. 1.
  [ ASSESSED VALUE ]  ──► Value after applying Save Our Homes (SOH) or 10% caps.
  [ EXEMPTIONS ]      ──► Homestead ($25k-$50k), senior, disability, or veteran credits.
  [ PROPOSED TAXES ]  ──► Estimated taxes based on proposed municipal/school millage rates.
| Section on TRIM | What It Represents | Action Step |
| Just / Market Value | Estimated open-market cash value of the property. | Compare with recent comparable sales in your neighborhood. |
| Assessed Value | Taxable baseline capped by statutory limits (3% for Homestead). | Verify your cap is accurately applied year-over-year. |
| Exemptions Applied | Deductions reducing your final taxable value. | Ensure all eligible exemptions (Homestead, widow, veteran) appear. |
| Public Hearing Dates | Schedule of city and county budget hearings. | Note dates if you wish to speak on proposed municipal millage rates. |
If something about your assessed valuation seems inconsistent with current neighborhood sales, there is a strict 25-day deadline from the mailing date to file an inquiry or formal petition with the Value Adjustment Board (VAB).
Smart Purchasing Strategy: Your Next Down Payment May Already Be in Your Portfolio
Managing holding costs on existing properties is only half the equation—leveraging your capital intelligently for your next purchase is the other.
When buying luxury, coastal, or second-home real estate, many buyers assume financing options are limited to three conventional routes:
-
Securing a traditional mortgage.
-
Paying outright with existing cash reserves.
-
Liquidating market investments or stock positions to raise cash.
                 STRATEGIC REAL ESTATE LIQUIDITY

  [ CONVENTIONAL PATH ] ──► Liquidate stocks/bonds ──► Pay capital gains taxes ──► Lose market growth
  [ PORTFOLIO LENDING ] ──► Pledge securities (SBLOC)──► Retain asset ownership ──► Access instant liquidity
The “Fourth Option”: Securities-Backed Lines of Credit (SBLOCs)
For qualified high-net-worth investors and luxury home buyers, financial institutions offer portfolio-backed lending, commonly known as a Securities-Backed Line of Credit (SBLOC).
An SBLOC allows you to access immediate liquidity using your eligible, non-retirement investment portfolio as collateral without selling the underlying securities.
-
Avoid Capital Gains: Retain your investment positions without triggering a taxable event.
-
Stay Invested: Your capital remains active in the market, continuing to generate dividends and compound growth.
-
Speed & Flexibility: SBLOC funds can be drawn quickly, allowing buyers to write competitive, non-contingent cash-equivalent offers.
Before liquidating long-term investments for your next property acquisition, ask your wealth manager or CPA: “Is there a more tax-efficient way for me to access liquidity against my existing portfolio?”